For business owners, HR leaders and CFOs, employee benefits planning has become an increasingly difficult balancing act. You want to offer a compensation package that helps you attract and retain employees, but the cost of maintaining core medical coverage continues to climb.
Voluntary benefits provide another option, one that lets you make additional coverage available with little or no direct premium cost to your company, while giving your employees the choice to purchase protection based on their individual needs.
Key Takeaways
- Voluntary benefits are employee-elected, often employee paid benefits – such as accident insurance, critical illness insurance, hospital indemnity insurance, life insurance and disability income insurance – that supplement core medical and retirement plans.
- Rising premiums – average family coverage cost $26,993 in 2025 – make voluntary benefits important for employers who want to expand the benefits package without taking on another open-ended medical expense.
- Offering voluntary benefits lets your employees choose protection that fits their risks and budget, while you keep tighter control over benefit costs and avoid a one-size-fits-all approach.
- Successful voluntary benefits programs focus on a curated set of options plus clear, ongoing employee education at open enrollment and throughout the year.
- Working with an experienced advisory partner can help you design, implement and communicate voluntary benefits so they truly support recruitment, retention and financial wellness across your workforce.
What Are Voluntary Benefits?
Voluntary benefits are supplemental insurance and perks you can offer your employees in addition to core benefits like health insurance, retirement plans and basic life insurance. Your employees choose whether to enroll and typically pay some or all of the premium through payroll deductions. These voluntary benefit options can include both insurance products and non-insurance products such as financial counseling or wellness programs.
Voluntary benefits are now a standard part of the benefits landscape, and they are still growing. In Gallagher’s 2026 Benefits Benchmarks survey of 3,717 U.S. organizations, nearly 1 in 3 employers said they plan to expand their voluntary benefit offerings over the next two years, most often to offer a more comprehensive benefits package (72%) and to address coverage gaps (66%). You may also hear supplemental and ancillary benefits used interchangeably with voluntary benefits. Here’s how they relate:
- Voluntary benefits describes how a benefit is offered: your employees choose whether to enroll and usually pay some or all of the premium.
- Supplemental benefits describes what the coverage does: it supplements core insurance or helps address financial gaps that core coverage may leave. Think of it as supplemental insurance that works alongside your primary plan.
- Ancillary benefits is a broader industry term for benefits offered alongside major medical coverage, such as dental insurance, vision insurance, life insurance and disability coverage.
A critical illness policy, for example, can be all three: an ancillary benefit offered alongside medical coverage, supplemental health protection against the financial effects of a serious illness, and a voluntary benefit when the employee elects and pays for it.
Employers are not necessarily required to pay the premium for voluntary benefits. Your role may be to select the options, facilitate enrollment and make payroll deductions available, though you can also choose to contribute toward the cost (more on that below). Availability, underwriting and portability depend on the carrier and policy.
Why Voluntary Benefits Matter in Today’s Cost Environment
The numbers illustrate the pressure. According to KFF’s 2025 Employer Health Benefits Survey, average annual premiums reached $9,325 for single coverage and $26,993 for family coverage. Family premiums increased 6% in one year, while employees contributed an average of $6,850 toward family coverage. Among covered workers with a general annual deductible, the average single-coverage deductible was $1,886.
When renewal increases consume more of your budget, simply adding employer-paid benefits may not be realistic. Cutting benefits or shifting more costs to employees, however, can make your benefits package less competitive and leave many workers with greater financial exposure. Voluntary benefits help cover gaps that standard health insurance leaves, without requiring you to fund richer core plans.
Even with “good” medical plans, deductibles, coinsurance and out of pocket expenses can hit hard, and that financial stress tends to show up in morale, retention and productivity. Economic uncertainty and post-COVID expectations have pushed more employees to look to employers like you for help managing financial risk.
Voluntary benefits respond to this environment by:
- Filling financial gaps around accidents, critical illness, hospital stays and loss of income
- Giving your employees access to group rates and discounted rates that may not be available on the individual market
How Voluntary Benefits Help Employers Control Costs
Voluntary benefits rarely move claims off the medical plan. Medical insurance remains primary for covered treatment. Instead, they let you provide additional choices without assuming the full financial burden of every option for every employee. Here is how that works in practice:
Expand the benefits package without proportionally expanding the budget. With employee paid coverage, employees fund the protection they select, so your company can offer a diverse range of supplemental health plans while its own share of the cost stays fixed – or at zero.
Make budgets more predictable. If you want to contribute to your employees’ supplemental benefits, you can use a defined contribution or fixed monthly allowance. This gives you a more predictable financial commitment than promising to absorb an unlimited percentage of future premiums, which can grow aggressively with enrollment and claims.
Reduce pressure for a one-size-fits-all package. A multigenerational workforce rarely wants the same coverage. Younger employees may value accident coverage, parents may prioritize life insurance and hospital indemnity, and employees approaching retirement may focus on critical illness or disability income insurance.
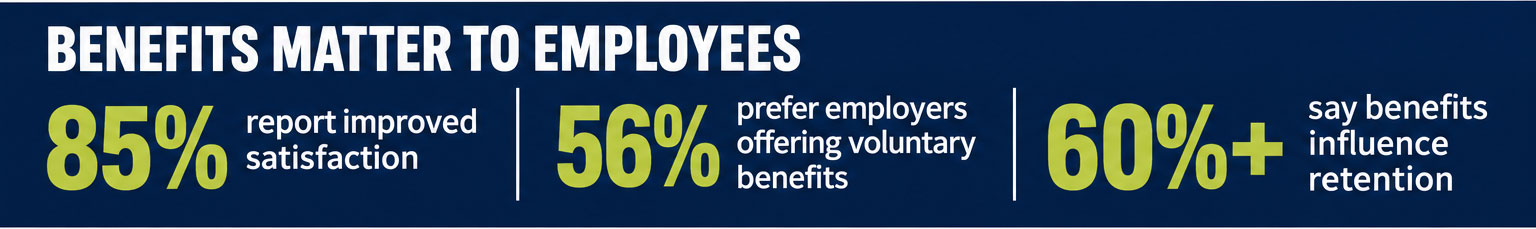
Support recruitment and retention. Research from EBRI’s 2025 employer study found that 85% of organizations offering voluntary benefits reported improvements in employee satisfaction. Additionally, 31% of employers use voluntary benefits for recruitment and retention, 56% of employed Americans prefer staying with employers offering voluntary benefits, and over 60% of employees say benefits influence their retention decisions. A well-designed voluntary program can help your smaller or midsized company’s compensation package feel more complete, helping you attract and retain talent even when you cannot match larger organizations dollar for dollar.
Encourage preventive care. Some supplemental health policies include wellness or screening benefits that pay a fixed amount – often $50 to $200 per person per year – when the insured completes an eligible preventive service. That gives employees a reason to stay on top of screenings and a way to get value from the policy even in a year without a major claim, sometimes enough to offset much of the premium.
Common Types of Voluntary Benefits to Consider
You do not need to offer every possible voluntary benefit. Instead, build a focused menu aligned with your workforce demographics and existing coverage. Common voluntary benefits examples include:
- Accident insurance: It provides cash benefits for uncovered medical expenses related to covered injuries-such as emergency room visits, fractures, ambulance transport and follow-up care. These payments can help your employees manage a medical deductible as well as nonmedical costs during recovery.
- Critical illness insurance: This coverage pays a lump sum upon diagnosis of covered conditions such as heart attack, stroke or cancer. Employees can generally decide how to use the money-toward medical cost-sharing, travel to treatment, childcare, household bills or reduced income during recovery. Policies may offer multiple payout events subject to policy rules and limitations.
- Hospital indemnity insurance: Hospital confinement indemnity insurance pays daily benefit amounts for hospital stays, including admission and confinement events. Benefits are based on the policy schedule rather than the hospital’s total bill. This indemnity insurance is especially relevant when your employees are enrolled in plans with substantial deductibles.
- Life insurance: Voluntary life insurance allows your employees to purchase additional protection beyond any employer-paid basic coverage. Options may include term life, permanent life and dependent coverage. Your employees can keep their coverage when changing jobs if voluntary benefits are portable, though portability and conversion terms vary by carrier. Evidence of insurability may be required beyond guaranteed-issue amounts offered during open enrollment.
- Disability income insurance: It covers monthly expenses if an employee is unable to work due to a covered illness or injury. Short-term disability addresses a limited period, while long-term disability may continue for a longer benefit duration. This is different from workers’ compensation, which generally applies only to work-related injuries.
- Dental and vision insurance: These can be voluntary when your employees elect and pay for coverage, helping with routine and significant dental or vision expenses subject to networks, benefit limits and waiting periods.
- Other voluntary benefits: Depending on your organization, you may also consider student loan repayment programs, identity theft protection, legal services, pet insurance, employee assistance programs, financial wellness resources and mental health support. Student loan repayment help and pet insurance are among the fastest-growing additions to voluntary benefit menus.
Designing and Implementing a Voluntary Benefits Strategy
The best program is the one your employees can understand, afford and use – not the one with the longest product list.
Voluntary benefits work best when integrated into an intentional benefits strategy rather than added ad hoc at the last minute. Here is a practical step-by-step process:
- Review your current program. Identify what your medical, life and disability plans cover, where your employees face financial exposure and what questions HR receives most often. Then examine usability: Is enrollment straightforward? Are deductions accurate? Can your employees find their policy information? Is the claim process understandable? Does the carrier provide useful reporting and responsive service?
- Survey employees. Use surveys, enrollment data and workforce demographics to understand which protections your employees value most. Avoid assumptions based on age or job title alone.
- Select a focused group of options. Compare carriers on plan design, exclusions, benefit schedules, portability, claim processes and digital tools-not just premium rates. Evaluate whether your plan offers guaranteed-issue provisions during initial eligibility periods.
- Decide how costs will be shared. The program may be fully employee-paid, partially employer-funded or supported through a fixed monthly allowance. Confirm tax and compliance implications-including ERISA and Section 125 pre-tax salary reduction rules-with appropriate benefits, tax and legal advisers.
- Integrate administration. Coordinate eligibility files, payroll deductions, billing and reconciliation. Consider using benefits administration platforms to keep the program from becoming time consuming for HR.
- Measure and refine. After the first enrollment, track participation by product, claims activity and employee feedback. Low uptake usually points to a communication problem or a product that doesn’t fit, so review your voluntary benefits lineup at each renewal and replace what isn’t working.
- Consider working with a third-party benefits enrollment firm. They can assist in the implementation, communication and enrollment of the new voluntary benefits. Enrollment firms, such as National Enrollment Partners, have licensed, professional benefits counselors that have experience explaining to employees the value of voluntary benefits and how they compliment an employee’s overall benefit choices.
Helping Employees Understand and Use Voluntary Benefits
Voluntary benefits only deliver value when your employees understand what each product covers, what it does not cover and how it fits alongside core health and retirement plans.
- Education at open enrollment: Use plain-language benefit guides, side-by-side plan comparisons and real-life scenarios. For example, show how hospital indemnity might help during a 3-day hospital stay with a $2,000 deductible, or how critical illness coverage could provide a financial safety net after a heart attack diagnosis.
- Decision support: Provide simple tools-checklists, short videos, webinars or one-on-one consultations-that help your employees decide whether coverage like critical illness or disability income insurance fits their family and budget.
- Year-round communication: Remind your employees about voluntary benefits during key life stages (marriage, birth, home purchase) and at midyear, not just during open enrollment. This reinforces relevance and encourages appropriate changes after qualifying events.
- Claims support: Provide clear instructions on how to file claims, how benefits are paid (lump sum versus ongoing payments) and typical timelines. Employees should not be surprised when they need to use accident or indemnity insurance.
- Equity and access: Consider multiple communication formats-digital, print, in-person-and languages where appropriate so all your employees, including remote and frontline workers, can understand their options.
Need help with benefits enrollment?
How Voluntary Benefits Support Employees’ Financial Well-Being
Your budget is only half of the equation. A voluntary benefits plan works when it gives your employees practical value and reduces their financial burden during unexpected events.
Financial protection beyond medical bills: Because accident insurance, critical illness and hospital indemnity plans typically pay cash directly to the employee (subject to policy terms), the money can cover whatever the event disrupts – including household bills and lost income that major medical insurance never touches. Life insurance and disability income insurance play a critical role in protecting long-term financial security for families, particularly in households where employees have limited emergency savings.
Convenient access: Employees can evaluate options during a coordinated enrollment and pay premiums through payroll deductions.
Potential group advantages: Beyond group rates, workplace plans may offer simplified or guaranteed-issue underwriting. This can be especially valuable for employees with health conditions or family histories that might make individual coverage expensive or difficult to obtain.
Coverage for family members: Some plans allow your employees to elect coverage for a spouse or dependent children.
Voluntary does not mean automatically affordable or appropriate for everyone. Your employees should consider their budget, emergency savings, current insurance, exclusions and the likelihood that a policy addresses a meaningful risk. Clear education helps your employees make informed decisions about where to direct their resources.
Common Voluntary Benefits Mistakes to Avoid
Even well-intentioned voluntary benefits programs can underperform. Three missteps come up often:
- Duplicating coverage employees already have. If your core health insurance or employer-paid life plan already addresses a risk, stacking a similar voluntary policy on top adds payroll deductions without adding much protection. Map existing coverage before adding products.
- Letting voluntary and traditional plans drift apart. Raising the medical deductible at renewal without revisiting accident or hospital indemnity benefit levels can leave voluntary benefits too small to close the new gap. Review both together each plan year.
- Underestimating the administrative load. Ask carriers about administrative fees, billing formats and reconciliation support up front. A low premium means little if HR spends hours each month correcting deduction errors or chasing enrollment changes.
Partnering With an Advisor to Build the Right Voluntary Benefits Package
The market for voluntary benefits and supplemental health coverage is complex. Professional guidance helps you avoid duplicated coverage, gaps and administrative headaches, and using one advisor for both core and voluntary benefits keeps onboarding, communication and service in one place. The right insurance partner can help you:
- Evaluate voluntary benefit options early in your renewal process. Don’t wait till the final renewal meeting with your advisor when major medical decisions need to be made. Ask your advisor to schedule a meeting with the carrier representative of your current disability and life benefits to discuss their voluntary benefit options and how they integrate with your current disability and life plans.
- Benchmark your offerings against similar companies, interpret carrier proposals and align voluntary options with your organization’s culture and budget.
- Plan communications, employee education and enrollment support so HR teams are not overwhelmed during open enrollment.
- Structure voluntary programs that are simple to administer, integrate with existing benefits technology and provide clear data on participation and employee feedback over time.
If you are looking for an experienced advisor, Hilb Group can help you evaluate your current benefits, identify potential gaps and build a voluntary benefits strategy around your workforce and business goals. Our team supports more than product selection-we help you coordinate carriers, enrollment, employee education and ongoing service so your employees and their family members can better understand their options and use the benefits they select. For questions about voluntary benefits, contact Marc Grove at mgrove@hilbgroup.com.
Frequently Asked Questions
The following questions address common, practical concerns that may not be fully covered above. This information is general and should not be treated as legal or tax advice.
Eligibility generally follows the same rules as your core employee benefits. Most of your full-time employees, and in some cases part-time staff, can elect voluntary coverage once they meet the waiting-period requirements you specify. The primary enrollment opportunity is your annual open enrollment period, with special enrollment windows after qualifying life events such as marriage, birth or adoption of a child, or loss of other coverage. Some carriers offer guaranteed-issue amounts-for example, a set amount of life insurance-only at initial eligibility or during designated enrollment periods, which your employees should pay attention to.
Tax treatment varies for employers. Administrative costs are often deductible as a business expense, but whether voluntary benefits tax deductible treatment applies to premiums depends on whether you are contributing and on the benefit type. Many voluntary benefits can be paid with pre tax dollars through a Section 125 cafeteria plan, which reduces your employees' taxable income, while others must be paid with post-tax dollars. The exact voluntary benefits tax treatment of specific products-such as group term life insurance over $50,000, disability income benefits and indemnity payments-is complex and should be confirmed with a tax advisor.
No. Voluntary benefits do not replace ACA-compliant major medical coverage and are not designed to meet minimum essential coverage requirements. Products like accident insurance, hospital indemnity and critical illness are intended to complement core health insurance by providing cash benefits when covered events occur, helping your employees manage deductibles and other out of pocket expenses. Your employees should not drop or downgrade essential medical coverage solely because they have supplemental health or indemnity insurance.
Yes. Many carriers now offer voluntary benefits with low or no minimum employee participation requirements, making them accessible even if your company has fewer than 10 employees. Digital enrollment platforms and broker support can significantly reduce the time consuming aspects of administration, such as managing payroll deductions and enrollment changes. You can start with one or two high-impact options-such as life insurance and accident or critical illness coverage-before expanding as employee interest grows. Because employees pay most or all of the premium, the advantages of a voluntary strategy apply regardless of company size.
Your employees should first ensure they are enrolled in core medical coverage and contributing enough to capture any available employer match in retirement plans. From there, a practical order of consideration is income protection (disability income insurance), family protection (life insurance), and then supplemental health coverages (accident, critical illness, hospital indemnity) for out-of-pocket medical costs. You or your advisor should provide simple decision aids-such as checklists or short questionnaires-to help your employees match voluntary benefits to their specific needs and budget during open enrollment. Many employees find that even modest payroll deductions for voluntary coverage provide meaningful financial security when unexpected events occur.